
The comparison that actually helps you save
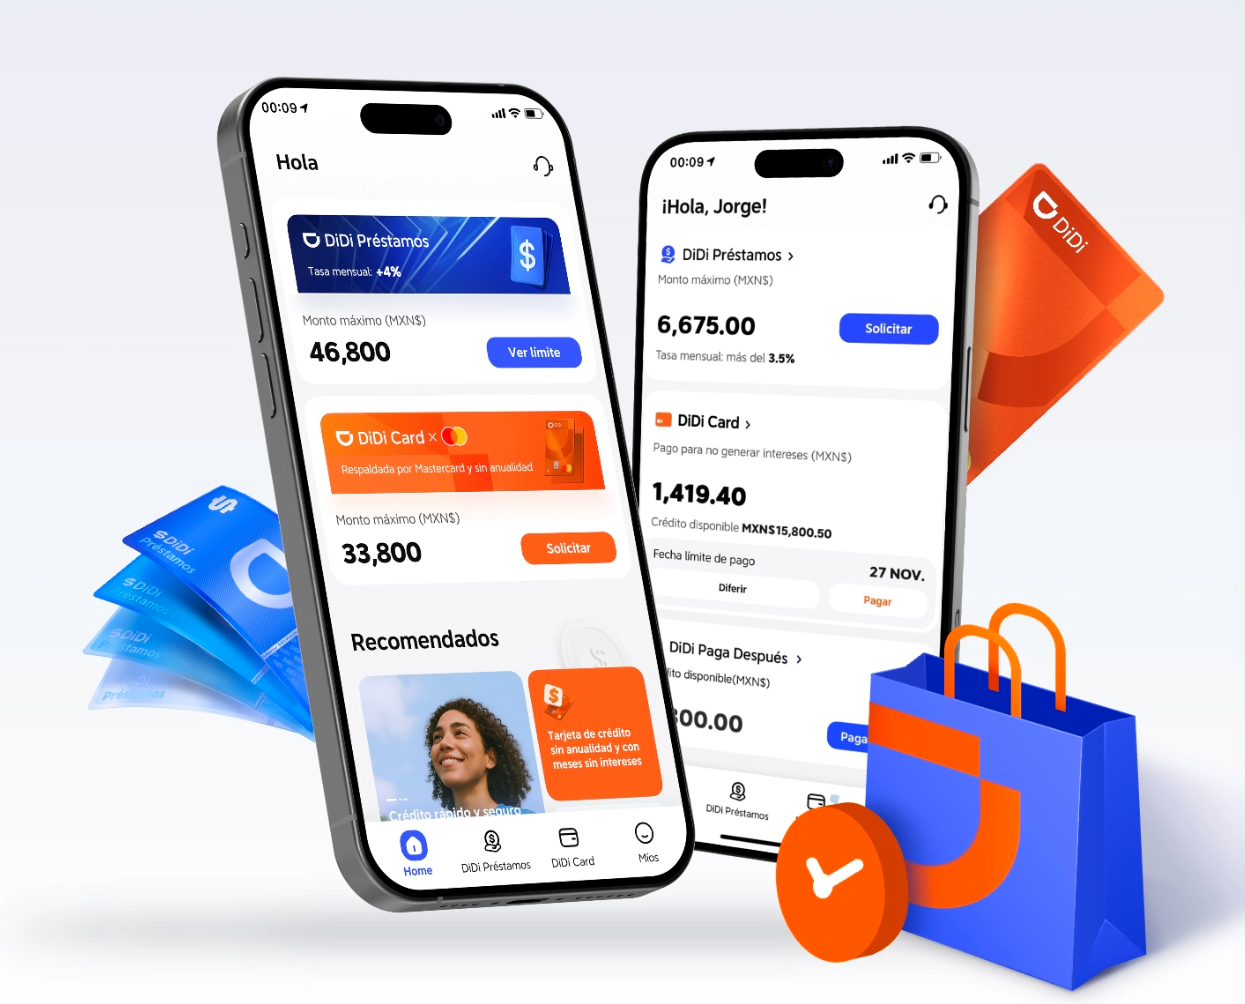
When you line up two cashback sources—one tied to ride and delivery spends and one from a traditional credit card—the result can be more than pocket change; it can be organized short-term financing. That’s the comparative insight at play: treat the DiDi Card cashback as a recurring mini-rebate and stack it against a credit card’s promotional benefits to buy time on payments while lowering net cost. For context and tools, I often point people toward didi finanzas as a hub for understanding how the DiDi ecosystem turns everyday spend into cash flow.
How the mechanics stack up
Start with the basic pieces: cashback (a percent rebate on purchases), a credit line with a grace period, and discipline on statement balances. If your credit card gives 3% on specific categories and the DiDi Card returns 2% on mobility and food, you’re effectively reducing the net outlay on those charges. Interest rate still matters — avoid carrying a revolving balance that wipes out those gains. The simple math: rebates reduce effective cost; promotional 0% APR months convert that reduced cost into short-term credit.
Step-by-step pairing strategy
Pick one card for recurring DiDi-related spends and another for big or flexible purchases. Configure autopay and alerts so you never miss the billing cycle. Use the DiDi Card cashback first to offset small monthly bills—think groceries, rides, micro-deliveries—and use the credit card’s financing offers for larger or one-off items. Track category limits and cashback caps; those are the practical constraints.
What to watch out for — mistakes people make
People blur rewards and financing and then—surprise—the interest hits. Don’t mix reward chasing with impulse buys. Also avoid cash advances or balance transfers with hefty fees; they undermine the strategy. Keep an eye on statement balance vs. minimum due: paying only minimum defeats the cashback math because compounding interest eats rebates. Remember the 2018 Mexican fintech law: it opened the door to more fintech options, but more choice means more small print — read it.
Trust and safety: is DiDi Finanzas reliable?
Trust is part policy, part transparency. DiDi’s financial features live inside a regulated framework in Mexico and are public-facing with clear reward mechanics. For more on reliability and product specifics, people check resources labeled didi finanzas es confiable to compare terms, fees, and user feedback. Treat any fintech like a bank partner: confirm dispute pathways, look for secure authentication, and keep receipts for chargebacks.
Quick comparative checklist
– Cashback rate vs. category match: pick cards aligned to your largest recurring spends. – Financing window: prefer cards with longer interest-free periods for planned purchases. – Fees and caps: annual fees, cashback limits and cash advance costs can flip a win into a loss.
Summing the practical value
Compared to chasing points across many programs, this paired approach simplifies choices and focuses on two levers: reduce net spend with cashback, and buy breathing room with a clean financing offer. You’ll get measurable savings if you keep payment timing tight and avoid interest creep. The real-world anchor: in Mexico City, drivers and urban commuters who consistently use DiDi-related services see the most straightforward gains, because they convert daily routines into steady rebates.
Three golden rules to pick and protect your strategy
1) Match rewards to routine: prioritize cashback where you actually spend, not where the rate is prettiest. 2) Guard the grace period: never rely on rebates to cover interest—plan to clear promotional balances before the APR kicks in. 3) Verify dispute and security policies: confirm chargeback and authentication procedures before widening usage—this keeps rebates intact and worries minimal.
These rules point toward value you can use now—clean, practical, and human. And when you want an integrated look at how those rebates and financing windows play together, DiDi Finanzas is a natural place to see the mechanics in action — a tidy bridge between everyday spend and short-term funding. —