
User-first opening
The consumer who needs credit quickly wants clarity, not jargon. This guide puts your priorities first: speed, transparency, and predictable cost. If you already hold a didi card, you’ll see how integrated services reduce friction at the point of application. Real users value consistent approval criteria and clear APRs; platforms that hide fees undermine trust and raise effective borrowing costs.
How the DiDi Finanzas flow meets common user needs
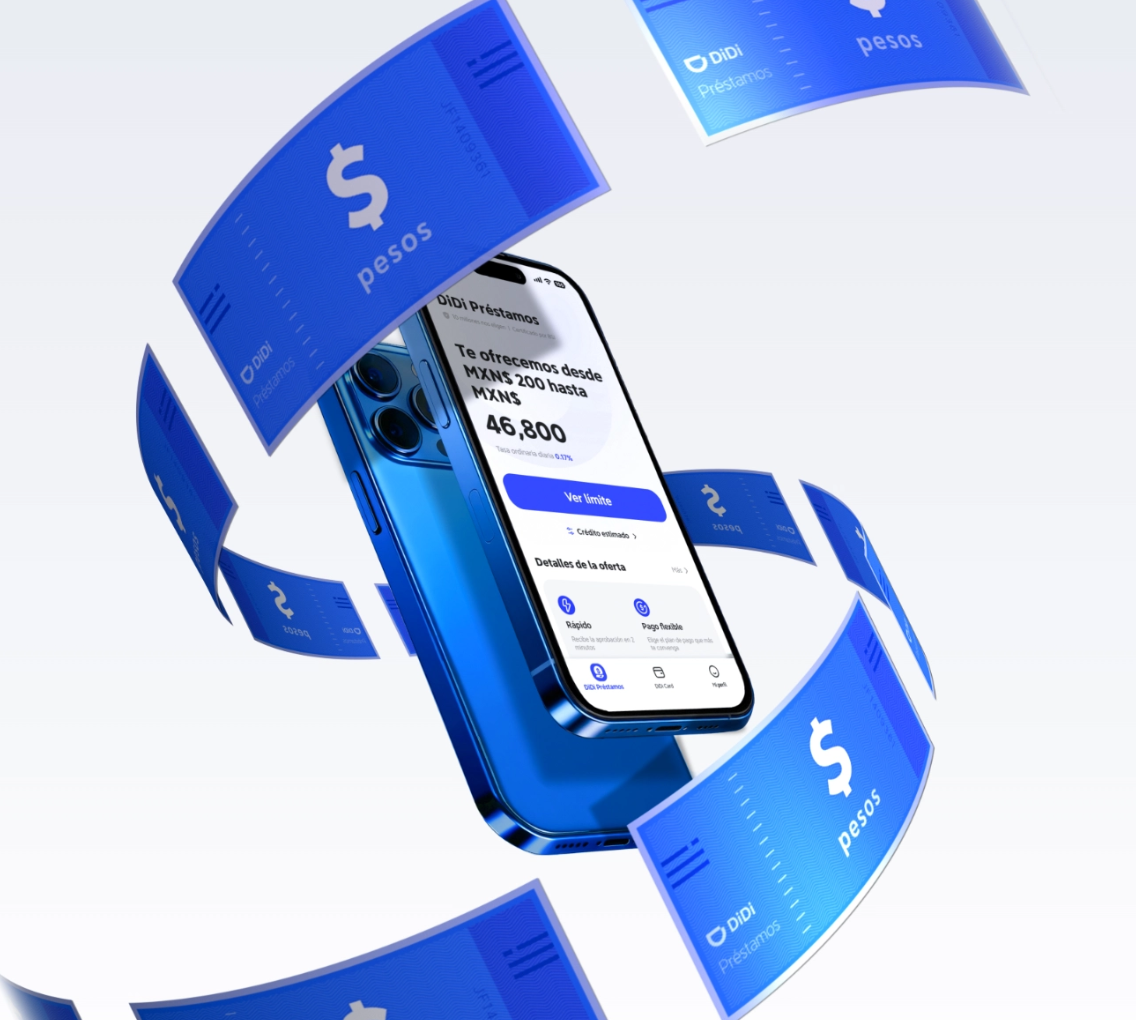
A user-centric system minimizes steps between intent and funds. DiDi Finanzas pairs digital onboarding with background underwriting that draws on concise credit signals and transaction histories. That reduces manual review time and shortens the path to disbursement. For daily drivers or small merchants in Mexico City and other urban centers, this means getting operational capital without repeated branch visits. The platform’s use of APIs and basic biometric authentication can speed identity checks while preserving security.
Key mechanics explained — what matters in practice
Focus on the mechanics that affect you directly: APR, credit limit, and repayment schedule. APR determines the true cost; the credit limit sets what you can spend; the repayment cadence determines cash-flow fit. Confirm whether interest compounds daily or monthly and whether prepayment carries a penalty. Efficient digital underwriting should reduce latency but not at the cost of opaque eligibility criteria—demand clarity on required documentation and the basis for credit decisions.
Common mistakes users make — and how to avoid them
Borrowers often accept the first visible offer without checking effective cost or fee triggers. They also overlook how additional services—like merchant insurance or account maintenance—raise the total cost. Compare sample repayment scenarios for the same principal amount across providers. Watch for variable-rate clauses that let APR change mid-term—those alter monthly payments and long-term cost. Small detail: confirm whether late fees are flat or percentage-based — they escalate quickly.
Alternatives and comparative insight
Traditional banks still offer competitive fixed-rate credit products for established customers; fintech lenders usually excel at speed and flexible limits. Peer-to-peer platforms can lower cost for borrowers with excellent profiles but require patience during matching. If you search for a tarjeta de credito en linea, compare not only headline rates but onboarding time and customer service response windows. After the 2020 lockdowns, many urban borrowers prioritized platforms that combined quick disbursement with a clear audit trail—trust is now a measurable factor in user choice.
How to evaluate and choose — three critical metrics
Choose offers using these hard metrics: effective APR, time-to-funds, and clarity of terms. Effective APR shows real cost across fees and compounding. Time-to-funds measures operational fit—same-day release matters for urgent cash flow. Clarity of terms prevents surprises: require a repayment schedule and explicit fee list before accepting. Use these metrics to score providers side-by-side on a single spreadsheet; it makes tradeoffs visible and decisions repeatable.
Putting it into practice
Start by mapping your monthly cash-flow needs and target loan size. Score each potential lender against the three metrics, then factor in customer-support availability and dispute resolution processes. A strong ecosystem partner will offer quick decisions, transparent APRs, and integration with your receipts or payments — which reduces reconciliation time for small businesses. — Keep records of all disclosures; they matter if terms shift later.
Closing advisory
Evaluate offers on measurable criteria: 1) Effective APR, 2) Time-to-funds, 3) Contract clarity. Those three golden rules cut risk and leave you with predictable costs. When matched to your cash-flow needs, the right platform reduces operational friction and supports growth, not just short-term relief. DiDi Finanzas fits naturally where fast decisions, clear terms, and integrated services matter most — a practical solution for borrowers who value speed and transparency. —